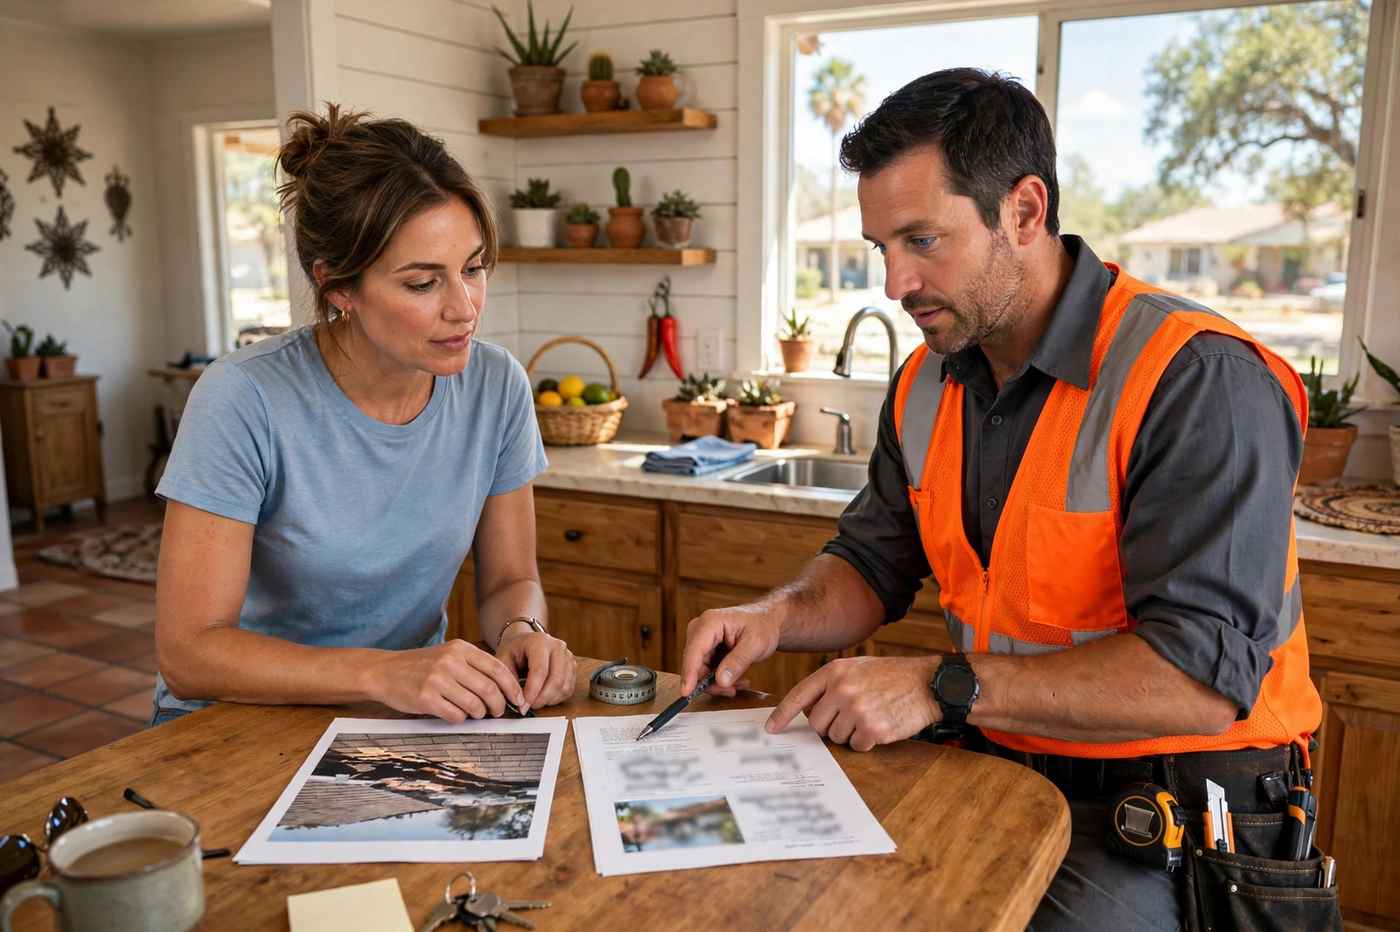
Damage Documentation
We document the damage slope by slope, marking and photographing every hit, so the scope your insurer reviews matches the roof instead of guessing at it.
Insurance claims help is documentation, not representation. We photograph the damage, write the scope, meet the adjuster on site with the evidence, and support the supplement with the facts the roof shows.
We document the damage slope by slope, marking and photographing every hit, so the scope your insurer reviews matches the roof instead of guessing at it.
We write a scope, not a verbal estimate, naming the damaged slopes and the material, so the document can be read by an insurer, an adjuster, or a buyer without a translation.
We meet the adjuster on site with the photos and the written scope, and we discuss the technical facts the roof shows, slope by slope.
We support the supplement with the facts the roof shows, when the scope misses a damaged slope or new damage is found once the roof is opened.
We re-inspect when the scope changes or a claim was denied, and we document the second look with the same care as the first.
What we do not do is the other side of the work: you file the claim, we document the damage, and we do not promise an outcome, because the decision belongs to your insurer.
Insurance claims help in San Antonio really involves the evidence and the deadlines. A replacement-cost policy pays current prices, while an actual-cash-value policy subtracts depreciation, and on a replacement-cost policy the carrier typically pays in two parts, the depreciated amount first and the rest once repairs are under way. The carrier has 15 days to acknowledge a claim, 15 business days to accept or reject it once it has what it asked for, and 5 business days to pay an accepted claim. Your policy sets your own reporting deadline, so the notice section is the one to read.
The second thing is the deductible. Your deductible is your responsibility under Texas law and your policy, and no roofer can waive it, absorb it, or pay any part of it for you. Texas law also keeps the roles separate: a roofing contractor may not act as a public insurance adjuster, a rule set out in Texas Insurance Code section 4102.163. We document the damage; your insurer or adjuster decides the claim. If the damage is hail, start with hail damage roof repair; if it is wind, start with wind damage roof repair.
How our insurance documentation process works: document first, scope second, meet third, so the claim is built on evidence.
Schedule
Call (254) 645-5833 during hours and tell us when the storm was and what you are seeing. We set a time to inspect, and the inspection covers every slope and the attic side of the deck.
Diagnose
We inspect the roof slope by slope, mark and photograph the hits, and check the flashing and the vents, so the scope is written from the roof, not from memory.
Fix
You get a written scope for the claim documentation, naming the damaged slopes and the material, with the photos to back every line of it.
Finish
We finish the documentation, hand you the scope and the photos, and meet the adjuster on site with the evidence when the visit is scheduled.
Moisture meter
We use the moisture meter on every insurance documentation visit, because a deck that looks dry from above can be damp underneath, and a damp deck is part of the damage the scope has to name.
Infrared camera
The infrared camera is how we check insurance documentation work before it is covered up, so a soft spot or a missed nail is found while it can still be photographed.
Chalk for marking hail hits
On a claims job the chalk for marking hail hits earns its keep on the first slope, showing us what the eye alone would miss in San Antonio heat.
Camera for slope-by-slope photos
We use the camera for slope-by-slope photos on every claims visit, because the documentation is the scope, and the scope is what the roof actually needs.
Safety harness and roofing ladder
The safety harness and roofing ladder are how claims work is checked before it is covered up, so the steep slopes get worked without rushing.
Tape measure and speed square
On a claims job the tape measure and speed square earn their keep on the first slope, measuring the damaged areas so the scope names them plainly.
Slope by slope, with every hit counted and photographed
We follow slope by slope, with every hit counted on claims work, because the count is made on the roof, and the photos back it.
Photos your insurer or adjuster can review
Photos your insurer or adjuster can review is the rule on every claims job we do in San Antonio, not an upgrade and not an extra: the documentation is the scope.
Written scope, not a verbal estimate
For insurance claims help, written scope, not a verbal estimate is what keeps the claim straight, because a document can be read by an insurer, an adjuster, or a buyer without a translation.
Re-inspection when the scope changes
We follow re-inspection when the scope changes on claims work, because a scope that missed a slope or a claim that was denied deserves a second look, documented with the same care as the first.
01
What we do: We walk the roof slope by slope, mark and photograph the hits, and write the scope before you call your insurer, because a claim built on evidence starts with the evidence.
The homeowner gets a written scope for the claims documentation, with photos of the damage and a clear statement of what the storm did and what it did not.
02
What we do: We re-inspect the roof slope by slope, count the hits again, and write a second scope that names what the first one missed, with the photos to back it.
The roof is documented, the claims help is scoped, and the homeowner decides with the evidence in hand rather than a guess.
03
What we do: We re-inspect the roof with the same care as the first look, document the second look slope by slope, and write a scope that names what the denial missed.
The homeowner keeps photos of the damage and a written scope for the claims help, so the next step is a decision, not a guess.
04
What we do: We read the claim with you, slope by slope, and say plainly what the documentation shows, because a closing does not wait for a guess.
The claims scope is written, the photos are in hand, and the homeowner can act on the roof with the evidence in front of them.
San Antonio claims follow the city's hail calendar, and the calendar is short: March through May, when about 85 percent of the large-hail reports fall. The documentation is gathered in those months, slope by slope, before the roof is repaired.
Stone Oak
Stone Oak is one of the San Antonio neighbourhoods where insurance claims help work is shaped by the houses themselves, with 1990s and newer streets and HOA rules that name the material and the colour.
Thousand Oaks
Thousand Oaks homes bring their own insurance claims help pattern, with 1980s streets on their second or third roof, where the decision is usually about age, not about one storm.
Westover Hills
In Westover Hills the insurance claims help work follows the neighbourhood: far-west master-planned building from the 1990s onward, where newer large-format roofs are entering their first replacement window.
Encino Park
Encino Park is one of the San Antonio neighbourhoods where insurance claims help work is shaped by the houses themselves, with far-north streets along the Bulverde Road corridor.
Alamo Ranch
Alamo Ranch homes bring their own insurance claims help pattern, with far-west master-planned building from the 1990s onward, where newer large-format roofs face the open west.
Spring hail season, March through May
Spring hail season, March through May, shapes how insurance claims help work is done in this city, because about 85 percent of the large-hail reports fall in those three months.
ACV versus RCV, and when the difference is released
ACV versus RCV, and when the difference is released, is part of every claims job here: replacement cost pays current prices, actual cash value subtracts depreciation, and the rest is released once repairs are under way.
Insurer deadlines in your policy
When we plan insurance claims help work, insurer deadlines in your policy are on the list from the first look, because the carrier has 15 days to acknowledge, 15 business days to accept or reject, and 5 business days to pay an accepted claim.
Deductible is the homeowner’s responsibility
Deductible is the homeowner's responsibility shapes how insurance claims help work is done in this city, and the scope is written with that responsibility in mind.
Claim problems are usually documentation problems, and documentation is the work: a claim without photos is an argument, and a claim with photos is evidence.
Problem
Damage never photographed after the storm is the most common claim problem, because the roof is repaired before the evidence is gathered, and the scope is written from memory.
Our Fix
We photograph the damage never photographed after the storm slope by slope, so the scope is written from the roof, not from memory.
Problem
A scope that missed a damaged slope is usually a scope written from the ground, and the missing slope is found by walking the roof, not by looking at it.
Our Fix
We re-inspect the scope that missed a damaged slope, count the hits again, and write a second scope that names what the first one missed.
Problem
A denied claim that needs a second look deserves a second look, documented with the same care as the first, because a denial is a decision about the evidence, and the evidence can be gathered again.
Our Fix
We document the denied claim that needs a second look slope by slope, so the second scope names what the first one missed.
Problem
New damage found once the roof is opened is common on an ageing roof, because the deck and the underlayment hide what the finish does not show.
Our Fix
We document the new damage found once the roof is opened with photos, so the supplement is built on the facts the roof shows.
The insurer decides the claim, and the insurer decides on evidence. Photos taken slope by slope, a written scope, and a re-inspection when the roof is opened give the file something to decide on. See hail damage roof repair for what the damage itself looks like.
Photos your insurer can review
Photos your insurer can review is one of the reasons homeowners choose our insurance claims help, because the documentation is the scope, and the scope is what the roof actually needs.
A written scope, not a verbal estimate
A written scope, not a verbal estimate is built into the insurance claims help work, not added on top of it, because a document can be read by an insurer, an adjuster, or a buyer without a translation.
Re-inspection when the scope changes
With insurance claims help, re-inspection when the scope changes is the difference between a claim that stops at the first scope and a claim that follows the roof.
Roles kept separate and lawful
Roles kept separate and lawful is one of the reasons homeowners choose our insurance claims help: we document the damage, and your insurer decides the claim.
Kbron Roofing holds 5.0 out of 5 from 18 Google reviews, all 5-star. Reviewers name Rene Vargas as their contact and describe honest, no-pressure service. Read short verbatim excerpts from those reviews in the Insurance Claims Help testimonials below.
We document storm damage across San Antonio, slope by slope, and we keep the roles straight: we document, your insurer decides. Call (254) 645-5833 during hours.
Short verbatim excerpts from Google reviews by customers who chose our insurance claims help work. All five readable reviewers gave 5 stars two months ago; three are quoted below.
"He was so professional, walked me through the steps of how to make a claim with my insurance, and the whole process was super simple. The roof was installed in just one day, and the crew was incredibly clean and professional."
Donnovan Smith
★★★★★ · Homeowner, San Antonio · 2 months ago · Storm and wind repair, roof installation
"He worked with my insurance and made it so easy. Definitely recommend them to anyone, just hear them out because I am very glad I did."
Joshua Garza
★★★★★ · Homeowner, San Antonio · 2 months ago · Storm and wind repair, roof installation
"Rene took a genuine, zero-pressure approach. He is remarkably honest, transparent, and truly puts the customer's best interest first."
Imanii Roberson
★★★★★ · Homeowner, San Antonio · 2 months ago · Roof repair for storm and wind damage
Real answers to the questions we hear most often about insurance claims in San Antonio, including the difference between ACV and RCV.
Hail Damage Roof Repair is the natural next step after insurance claims help on a roof that needs more than one kind of attention.
View Hail Damage Roof RepairStorm Damage Roof Repair pairs with insurance claims help on many San Antonio homes, and the two scopes are written together so nothing is missed.
View Storm Damage Roof RepairWhere insurance claims help work raises a question, wind damage roof repair is often the answer, and we scope it in the same visit.
View Wind Damage Roof RepairRoof Inspection is the natural next step after insurance claims help on a roof that needs more than one kind of attention.
View Roof InspectionRoof Replacement pairs with insurance claims help on many San Antonio homes, and the two scopes are written together so nothing is missed.
View Roof ReplacementWhere insurance claims help work raises a question, permits and codes is often the answer, and we scope it in the same visit.
View Permits and CodesCall us at (254) 645-5833 or send a message and we will get back to you during business hours. We schedule claim documentation Monday to Saturday, 6 AM to 8 PM.
Phone
(254) 645-5833Address
6 Irongate Creek, San Antonio, TX 78238, United States, San Antonio, Texas
Hours
Mon–Sat: 6 AM – 8 PM